The Great Macro Inversion: Why the Bond Market is Sweating While Bitcoin Sleeps
By the Financial News Desk | Edited by Samuel Rae
Trusted Editorial Content: Reviewed by leading industry experts and seasoned editors.
Main Facts
In an unexpected twist that is currently puzzling macroeconomic strategists and derivatives traders alike, the global financial landscape is witnessing a profound behavioral inversion between traditional safe-haven assets and digital currencies.
The U.S. Treasury market—traditionally viewed as the bedrock of global liquidity and financial stability—is currently gripped by acute anxiety. Conversely, Bitcoin, an asset historically renowned for its violent price swings and outsized volatility, is trading with an eerie, uncharacteristic calm.
Recent market data highlights this stark divergence:
- The MOVE Index, which measures U.S. Treasury volatility, has surged dramatically from a baseline of approximately 80 earlier in the week to hover around 104. This marks its highest reading since March, signaling severe distress in government debt markets.
- The Cboe VIX, tracking expected volatility in the S&P 500 equity market, remains subdued near its yearly lows at roughly 14.
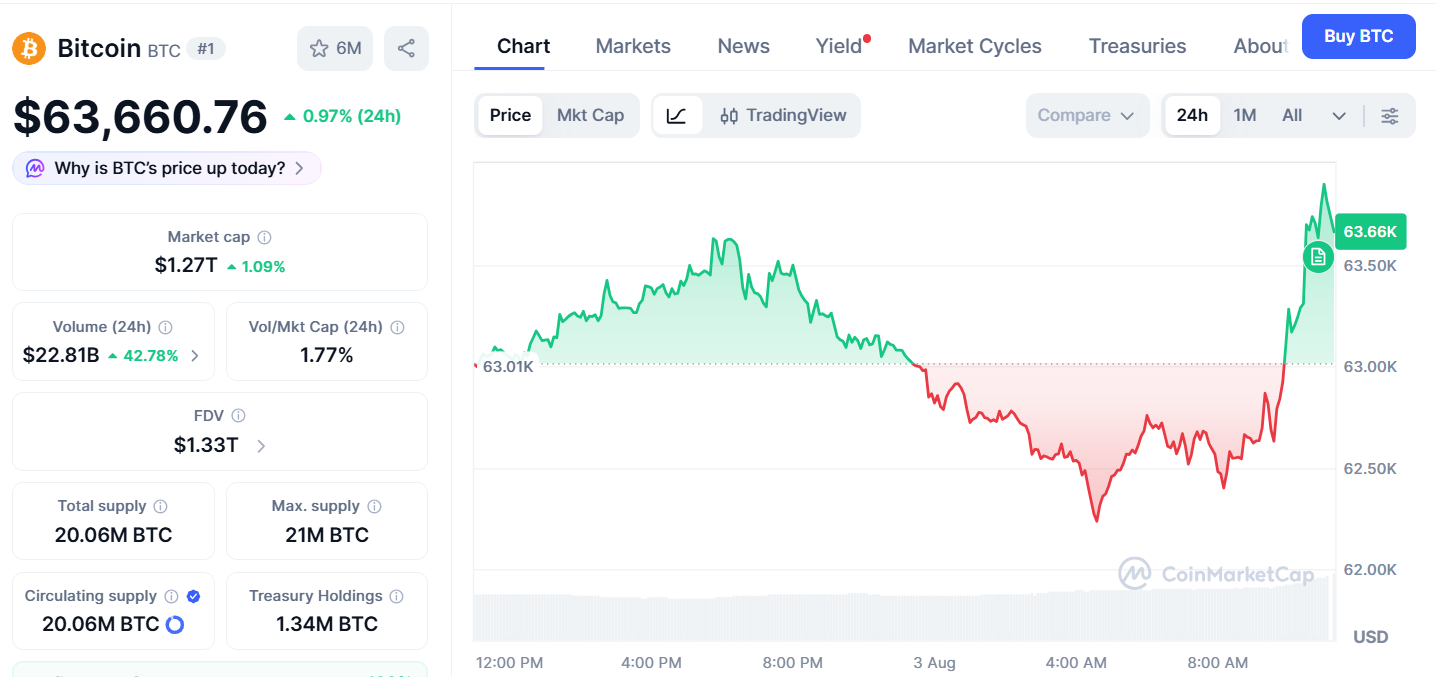
- Bitcoin Implied Volatility, as measured by Volmex’s 30-day BVIV index, is currently compressed near 37—sitting just a hair’s breadth away from its yearly low of approximately 35.
While macroeconomic headwinds have pushed the benchmark U.S. 10-year Treasury yield toward a blistering 5.2% before a minor retreat, the crypto options market is refusing to price in the kind of systemic panic that typically accompanies such turbulent debt conditions. For the first time in recent financial history, the "risk-free" asset class is behaving like the wild west, while the world’s premier cryptocurrency is showing signs of maturity—or at least, a temporary detachment from macro-driven chaos.
Chronology: How the Divergence Unfolded
To understand how traditional bonds and digital assets arrived at this peculiar crossroads, it is necessary to examine the cascading macroeconomic events of the past several weeks.
Early Week: The First Tremors in Fixed Income
The week began with mounting pressures in the energy sector and renewed worries over persistent inflation. As macroeconomic indicators pointed toward a potentially longer-than-expected period of elevated interest rates, institutional investors began aggressively repositioning their fixed-income portfolios.
By mid-week, selling pressure in the U.S. government debt market accelerated. The yield on the benchmark 10-year U.S. Treasury note breached psychological resistance levels, climbing steeply until it briefly touched the 5.2% threshold. This rapid upward movement in yields immediately triggered defensive positioning in the bond pits, sending the MOVE index on an upward trajectory from 80 to over 100.
Mid-Week: The Spillover That Didn’t Happen
Historically, a spike in Treasury yields and a collapsing bond market act as a wrecking ball across global risk assets. Higher yields inherently increase borrowing costs for businesses and consumers, siphon liquidity away from speculative markets, and raise the risk-free rate of return, making non-yielding assets less attractive.
As yields spiked, Bitcoin’s ongoing price rally visibly stalled. Market participants braced for the inevitable cascade—expecting leveraged long positions in crypto to get liquidated as broader financial conditions tightened.
However, the expected bloodbath in the crypto derivatives market failed to materialize. While Bitcoin’s spot price paused its upward momentum, options traders steadfastly refused to bid up the price of protective puts. Implied volatility indices for Bitcoin continued to drift downward rather than spike upward, defying decades of precedent where macro shocks instantly ignited crypto volatility.
Late Week: Decoupled Volatility Regimes
By the end of the week, market analysts confirmed a complete breakdown in traditional cross-asset correlations. The statistical relationship (correlation) between the MOVE index and equity/crypto volatility measures turned negative or flatlined near zero. Treasury traders were paying historic premiums to hedge against portfolio destruction, while Bitcoin traders were quietly sitting on some of the lowest expected volatility readings seen all year.
Supporting Data & Market Metrics
A deeper dive into the numbers reveals just how pronounced this anomaly has become across various asset classes:
| Market / Index | Indicator Name | Current Reading | Historical Context / Significance |
|---|---|---|---|
| U.S. Treasuries | MOVE Index | ~104 | Highest level since March; indicates severe turbulence and hedging demand in government bonds. |
| S&P 500 | Cboe VIX | ~14 | Hovering near yearly lows; equity markets remain remarkably sanguine despite bond stress. |
| Bitcoin | Volmex 30-Day BVIV | ~37 | Close to its 2026 low of ~35; options market pricing minimal near-term turbulence. |
| Macro Yields | U.S. 10-Year Yield | ~5.2% (Touched) | Rapid tightening sparking anxiety over federal borrowing costs and inflation persistence. |
The Mechanics of the Volmex BVIV Index
The Volmex Bitcoin Implied Volatility (BVIV) index functions similarly to traditional equity volatility gauges like the VIX, aggregating pricing data from options markets to determine what market participants expect Bitcoin’s price swings to look like over a rolling 30-day window.
At a reading of 37, the index indicates that options traders are pricing in relatively modest daily moves for Bitcoin relative to its historical average, which frequently sees annualized volatility metrics pushing well above 60 to 80 during macro transitions.
Official Responses and Expert Commentary
Market analysts, quantitative researchers, and macro strategists have offered varied interpretations of this unprecedented divergence.
Jane Street Macro Strategist (Anonymous Industry Note):
"We are looking at a fundamental shift in where institutional risk is concentrated. For years, the narrative was simple: when the macro environment gets rocky, dump crypto because it’s high-beta risk. But today, the structural buyers of Bitcoin—spanning spot ETFs, corporate balance sheets, and long-term HODLers—are absorbing supply differently. The structural plumbing of the bond market, burdened by heavy sovereign issuance and interest rate uncertainty, is where the real stress test is happening right now."
Derivatives Desk Head at a Major Digital Asset Fund:
"It’s a mistake to assume Bitcoin has suddenly transformed into a low-beta safe haven. What we are seeing in the options market is a temporary exhaustion of panic sellers coupled with a lack of directional catalysts. Traders aren’t buying upside calls, but they aren’t aggressively buying crash protection either. They are simply stunned by what’s happening in Washington and the Treasury market, treating crypto as a side-show while the primary debt engine stutters."
Senior Fixed Income Analyst:
"The move in the 10-year yield toward 5.2% is a direct referendum on fiscal dominance and structural inflation risks. When the MOVE index climbs to 104 while equity and crypto volatility sleep, it tells you that the structural machinery of global collateral—U.S. government debt—is experiencing plumbing issues that equity and digital asset markets haven’t fully priced in yet. Yet."
Implications for Global Investors
The decoupling of Bitcoin volatility from Treasury volatility carries profound implications for asset allocation, institutional portfolio management, and macroeconomic forecasting.
1. The Redefinition of "Risk"
For over a decade, financial textbooks categorized risk neatly: government bonds carried near-zero credit and volatility risk, while cryptocurrencies occupied the extreme outer edge of the risk spectrum.
The current environment turns this dogma on its head. When sovereign debt instruments exhibit volatility indices normally associated with speculative equities or emerging market currencies, institutional risk models must be rewritten. Portfolio managers who rely on Value-at-Risk (VaR) models are discovering that holding nominal sovereign debt is no longer the risk-free harbor it once was.
2. Crypto’s Maturation vs. Complacency
While some industry advocates point to Bitcoin’s subdued volatility as proof of its growing maturity and institutionalization, seasoned risk managers urge caution. A low-volatility environment in crypto often precedes explosive, out-of-nowhere directional breakouts.
If bond market stress eventually spills over into broader credit crunches or liquidity squeezes, Bitcoin may not remain immune forever. The current calm could be the proverbial eye of the storm.
3. Cross-Asset Contagion Risks
The breakdown in historical correlations does not guarantee that crypto will escape unscathed if the bond market crisis deepens. Should surging yields trigger a broader liquidity drain across the global financial system, forced deleveraging could easily drag digital assets down with equities and other risk-on sectors.
However, the fact that crypto markets have absorbed a spike in the 10-year yield up to 5.2% without a systemic liquidation event demonstrates a higher baseline of structural resilience than was evident during previous tightening cycles.
Conclusion
Bitcoin spent the better part of its existence acting as the definitive volatility trade of the modern era—a high-beta playground for speculators reacting to every twitch of the global economy. Today, the script has flipped. As the U.S. Treasury market grapples with structural debt anxieties, inflation stickiness, and a spike in the MOVE index, the world’s largest cryptocurrency is sleeping through the storm. Whether this tranquility represents a permanent decoupling or merely the calm before the next macro squall remains one of the most fascinating questions in modern finance.
Editorial Process: At Bitcoinist, our editorial standards center on delivering thoroughly researched, accurate, and unbiased content. We uphold strict sourcing standards, ensuring each page undergoes diligent review by our team of top technology experts and seasoned editors.