Bybit’s IPO Express Opens Tokenized Access to High-Profile Offerings: A Deep Dive into the Mechanics, Restrictions, and Market Implications of SPCX
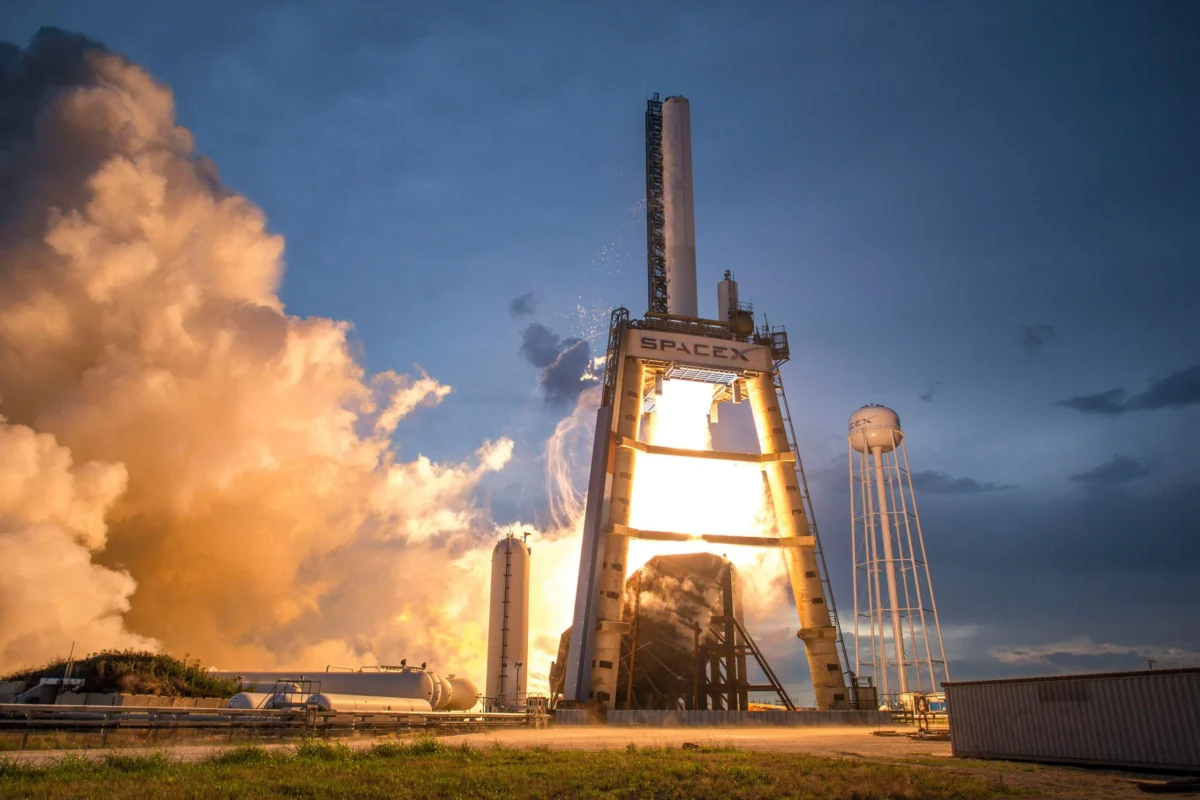
GLOBAL FINANCIAL MARKETS — Cryptocurrency exchange Bybit has officially entered the traditional equity landscape with the launch of its new "IPO Express" product. Designed to bridge the gap between digital assets and traditional Wall Street milestones, the product’s inaugural offering gives eligible users early access to tokenized shares of aerospace titan SpaceX.
However, the rollout has brought to light a complex web of execution rules, custody structures, strict geographic exclusions, and a fundamental debate over what tokenized equity actually represents for the modern retail and institutional investor.
Main Facts
Bybit’s IPO Express, launched on June 7, introduces a novel mechanism for cryptocurrency exchange users to participate in major traditional initial public offerings (IPOs). The product’s standout feature is its automated execution policy: if a user subscribes to an allocation and the final offering price lands within 20% of the indicative price they originally agreed to, the order is executed automatically without requiring any additional user confirmation.
The headline debut for IPO Express is SpaceX, trading under the ticker symbol SPCX. Subscriptions for the SpaceX tokenized offering run through June 11, with spot trading slated to open on June 12.
Crucially, the product relies on the xStocks platform, developed by Payward Services—the parent company of cryptocurrency exchange Kraken. Payward’s infrastructure has simultaneously allowed Kraken to open similar SpaceX IPO access to retail clients across more than 110 countries.
Despite utilizing blockchain rails, each SPCX token is claimed to be backed on a 1:1 basis by actual SpaceX equity held in regulated broker-dealer custody. This differentiates the product from synthetic pre-IPO perpetual contracts found on platforms like Hyperliquid and Binance, where no underlying shares physically change hands.
Nonetheless, owning SPCX does not equate to traditional corporate ownership. Bybit’s terms explicitly state that token holders receive:
- Zero voting rights at corporate shareholder meetings.
- Zero dividend rights or claims on company distributions.
- Zero direct legal or beneficial ownership in SpaceX equity.
Instead, holders acquire economic exposure to the price performance of the underlying stock—and nothing more.

Chronology
The timeline surrounding the launch of Bybit’s IPO Express and the highly anticipated SpaceX public offering highlights the rapid pace at which tokenization infrastructure is converging with traditional equity markets:
- Early June 2026 (Preparation Phase): Regulatory frameworks and infrastructure alignments via Payward Services’ xStocks platform are finalized, setting the stage for cross-platform retail access to private-turned-public tech giants.
- June 7, 2026: Bybit officially announces and launches the IPO Express product, naming SpaceX (SPCX) as its very first listing. Reuters and other major financial outlets report on the mechanism, while Kraken independently deploys similar infrastructure for its own retail user base.
- June 7 – June 11, 2026: The subscription window for eligible Bybit VIP and PRO users remains open. During this period, submitted funds are strictly frozen from the moment of order submission until allocation results are officially announced (or up to five business days in the event of cancellation).
- June 11, 2026: Subscription closes. Given the astronomical demand for the SpaceX offering, allocation algorithms calculate proportional distributions.
- June 12, 2026 (Upcoming): Spot trading for the SPCX token is scheduled to commence on Bybit, allowing secondary market price discovery for holders of the tokenized equity product.
Supporting Data and Market Dynamics
The appetite for SpaceX’s public debut has shattered conventional expectations, creating a hyper-competitive environment for both traditional and tokenized allocation channels.
- Demand vs. Supply Disparity: SpaceX’s IPO has reportedly drawn an astounding $150 billion in total demand against a target raise of roughly $75 billion. This massive oversubscription rate means that even qualified VIP and PRO subscribers on Bybit will likely receive only partial allocations of their requested SPCX amounts.
- Capital Lockup Constraints: Market participants must factor in liquidity friction. Funds committed to the IPO Express subscription are entirely frozen from the point of order placement until the final allocation results are published. If an offering is canceled, funds may remain tied up for up to five business days.
- Regulatory and Geographic Boundaries: Access to SPCX is heavily bottlenecked. Eligibility is restricted exclusively to Bybit users who have achieved VIP or PRO tier status—a threshold typically dictated by high monthly trading volume or substantial asset holdings—alongside mandatory completion of robust identity verification (KYC) protocols.
Furthermore, the product is completely unavailable to residents of the European Economic Area (EEA), encompassing all 27 EU member states alongside Iceland, Liechtenstein, and Norway. Bybit confirmed it holds no license or authorization under the Markets in Crypto-Assets (MiCA) regulation or other applicable EEA financial regimes to market this product.
These restrictions add layers of irony to the global rollout. While tokenized equity products are frequently marketed as borderless financial workarounds, they remain shackled by territorial compliance. For instance, while mainland Chinese and Hong Kong investors are already shut out of the SpaceX IPO due to US International Traffic in Arms Regulations (ITAR), the tokenized alternative route introduces its own impenetrable geographic blockades for European traders.
Official Responses and Platform Perspectives
Representatives from Bybit have framed IPO Express not as a one-off promotional event, but as the foundational rollout of a recurring, institutional-grade retail bridge. The exchange’s initial documentation and executive commentary emphasize that tokenized access to legacy financial milestones is the logical evolution of digital asset exchanges.
Industry observers note that the collaboration with Payward’s xStocks infrastructure signals a broader trend: centralized cryptocurrency exchanges are aggressively seeking to capture fee revenue from traditional capital markets by packaging equities into token formats.
While established brokerages view these tokenized wrappers with cautious skepticism—pointing out the lack of true shareholder rights—crypto-native platforms champion the friction-free secondary market liquidity and fractional exposure that tokens afford to high-net-worth retail traders who otherwise lack access to elite pre-IPO allocations.
Implications for the Future of Tokenized Assets
The launch of Bybit’s IPO Express and its headline-grabbing SpaceX listing carry profound implications for the future of finance, bridging distinct structural paths for both crypto and traditional equities:
- The Rise of "Economic-Only" Tokenization: By clarifying that SPCX holders possess no voting or dividend rights, Bybit has set a legal precedent for how tokenized equities will likely operate. Users are essentially trading derivatives of corporate performance wrapped in a tokenized receipt, rather than owning the underlying corporate asset. This protects issuers from complex shareholder registry overhead while still satisfying retail demand for equity exposure.
- Expansion Beyond SpaceX: Reports indicate that Bybit, Kraken, and other platforms utilizing xStocks architecture are already eyeing subsequent high-profile technology IPOs. Companies frequently mentioned in the pipeline include artificial intelligence heavyweights such as OpenAI and Anthropic. If successful, tokenized IPO access could become the standard playbook for tech giants looking to tap crypto-native liquidity pools during public offerings.
- Regulatory Fragmentation: The stark exclusion of European Economic Area investors under MiCA underscores the ongoing friction between borderless decentralized technology and localized regulatory enforcement. As tokenized traditional assets grow, platforms will face increasing pressure to either secure traditional broker-dealer licenses across multiple jurisdictions or erect even stricter geofencing walls.
- The Blurring Lines Between CeFi and TradFi: Ultimately, products like IPO Express demonstrate that the wall separating centralized cryptocurrency exchanges (CeFi) and traditional finance (TradFi) is rapidly crumbling. Whether this integration leads to a more democratized financial ecosystem or simply introduces new layers of opaque risk for retail traders remains the defining question for the next era of market evolution.