Massive $15.6 Billion Bitcoin Options Expiry Clears Without Causing Spot Market Turbulence
By the News Desk | Edited by Samuel Rae
Trusted Editorial Content — Reviewed by leading industry experts and seasoned editors.
Executive Summary & TL;DR
- The Event: Approximately $15.6 billion in Bitcoin (BTC) options contracts reached settlement on September 25, marking one of the largest single derivatives expiries of the year.
- The Outcome: Despite dire predictions of "max pain" and severe volatility, the spot market absorbed the massive clearance smoothly, with Bitcoin holding steady in the mid-$83,000 range.
- Market Structure: The expiry wiped out a hefty block of hedging exposure totaling roughly 182,000 BTC, with calls substantially outnumbering puts.
- Broader Implications: While Bitcoin cooled off from weekly highs near $87,000, capital rotated into prominent altcoins like XRP and Solana, signaling that investor risk appetite remained intact rather than facing a widespread flight from digital assets.
Main Facts: Deconstructing the $15.6 Billion Deribit Settlement
In the high-stakes world of cryptocurrency derivatives, few events strike as much fear into the hearts of retail traders as a multi-billion-dollar quarterly options expiry. On September 25, the crypto ecosystem faced its latest major trial by fire as roughly $15.6 billion in Bitcoin options reached their settlement date primarily through Deribit, the industry’s leading options exchange.
To put the scale of this event into perspective, the open interest heading into the settlement represented an astonishing 182,000 BTC. Market analysts and algorithmic trading desks had spent weeks bracing for potential turbulence. Options expiries of this magnitude typically carry the risk of triggering sudden, sharp price movements due to "gamma squeezing"—a phenomenon where market makers are forced to aggressively buy or sell underlying spot assets to rebalance their delta hedges as the asset price dances around critical strike prices.
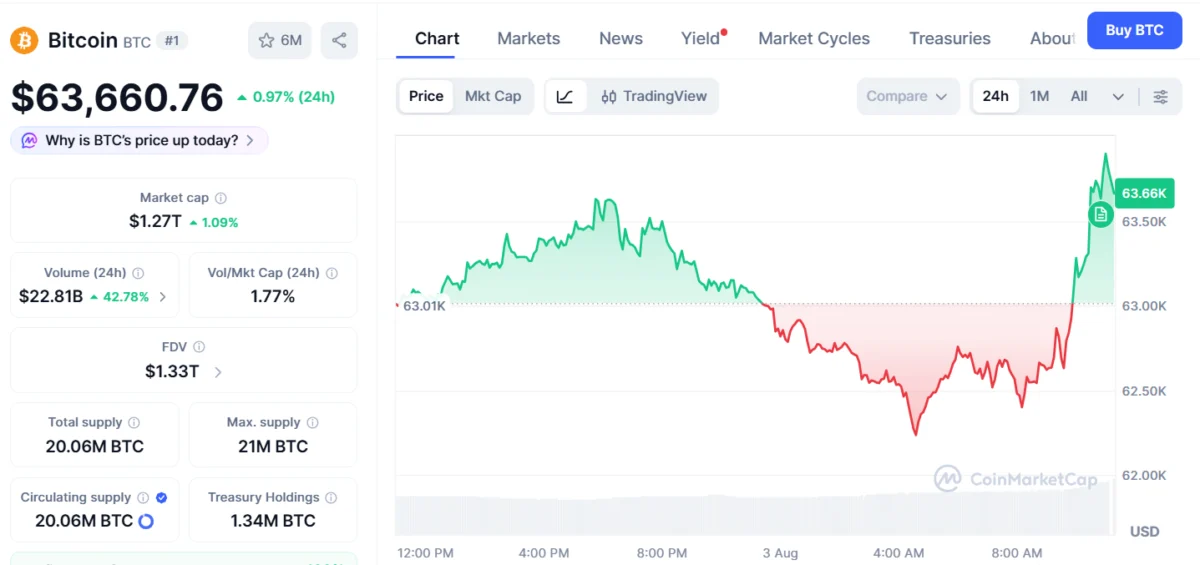
Yet, contrary to apocalyptic forecasts, the market executed a textbook landing. Bitcoin did not suffer a cascading flash crash, nor did it experience an explosive, artificial squeeze toward an improbable "max pain" target. Instead, the premier cryptocurrency gracefully absorbed the settlement shock, maintaining a resilient position in the mid-$83,000 territory.
The successful clearing of the September book marks the removal of a massive layer of structural friction. With these contracts now settled, options dealers and institutional trading desks have been relieved of the complex hedging burdens that defined their trading books throughout the previous quarter.
Chronology: How the September Expiry Unfolded
To fully understand how the market navigated this monumental financial event, it is helpful to trace the timeline leading up to, during, and immediately following the September 25 settlement.
Pre-Expiry Build-Up (Early to Mid-September)
Weeks before the official settlement date, open interest on Deribit and other major derivatives platforms began to swell. Analysts tracking the options book noted a distinct bias toward the bullish side. Call options (contracts giving the holder the right to buy Bitcoin at a set price) heavily outnumbered put options (contracts protecting against downside risk). Specifically, the open interest boasted roughly 106,200 BTC in calls compared to just 75,900 BTC in puts.
As Bitcoin rallied earlier in the week—touching an intraday high near $87,000—speculation reached a fever pitch. Commentators across social media and financial blogs warned that market makers would be forced to aggressively defend specific strike levels, potentially sparking wild intraday swings as the expiration hour drew closer.
The Peak and Intraday Pullback (September 23–24)
Hovering near the $87,000 threshold, Bitcoin faced natural profit-taking. Rather than maintaining its vertical ascent, BTC experienced a healthy cooling-off period, retracing down to the $83,600 zone. This pre-expiry consolidation actually served to deflate some of the speculative froth, reducing the intensity of the delta-hedging pressure that options dealers had to manage. By the time the clock ran down on September 25, much of the dangerous gamma exposure had already been neutralized by natural market drift and proactive position-rolling by sophisticated traders.
Settlement and Immediate Aftermath (September 25 and Beyond)
At 8:00 UTC on September 25, the contracts officially settled. The anticipated cascade of liquidations never materialized. Order books remained orderly, bid-ask spreads stayed tight, and spot markets absorbed the transition without missing a beat. Within 48 hours of the settlement, Bitcoin established a stable base around the mid-$83,000s, proving that the underlying spot demand was robust enough to stand on its own two feet without the artificial crutch—or anchor—of massive derivatives positioning.
Supporting Data: Analyzing the Open Interest and Market Mechanics
A common misconception among retail market participants is that a $15.6 billion options expiry equates to $15.6 billion physically changing hands or flooding into the spot market all at once. In reality, notional value is a theoretical figure calculated by multiplying the total number of underlying contracts by the current asset price.
Breaking Down the Numbers
- Total Notional Value Settled: ~$15.6 billion USD.
- Total Underlying Volume: ~182,000 BTC.
- Call Open Interest: ~106,200 BTC (demonstrating strong bullish sentiment heading into the quarter’s end).
- Put Open Interest: ~75,900 BTC (signifying baseline downside protection among institutional and whale accounts).
+-------------------------------------------------------------+
|              SEPTEMBER 25 BTC OPTIONS SETTLEMENT            |
+-------------------------------------------------------------+
| Total Notional Value  : ~$15.6 Billion                      |
| Total Volume          : ~182,000 BTC                        |
| Call Options (Bulls)  : ~106,200 BTC                        |
| Put Options (Bears)   : ~75,900 BTC                         |
+-------------------------------------------------------------+
The Mechanics of Dealer Hedging
Why do these quarterly dates matter so much if they don’t represent direct spot purchases? The answer lies in the mechanics of market-making.
When institutions sell options to clients, they often take the opposite side of the trade and must neutralize their directional risk. If a dealer sells a large block of call options, they buy spot or futures Bitcoin as the price rises (delta hedging) and sell as the price falls. This creates a feedback loop that can exacerbate volatility as an expiry approaches.
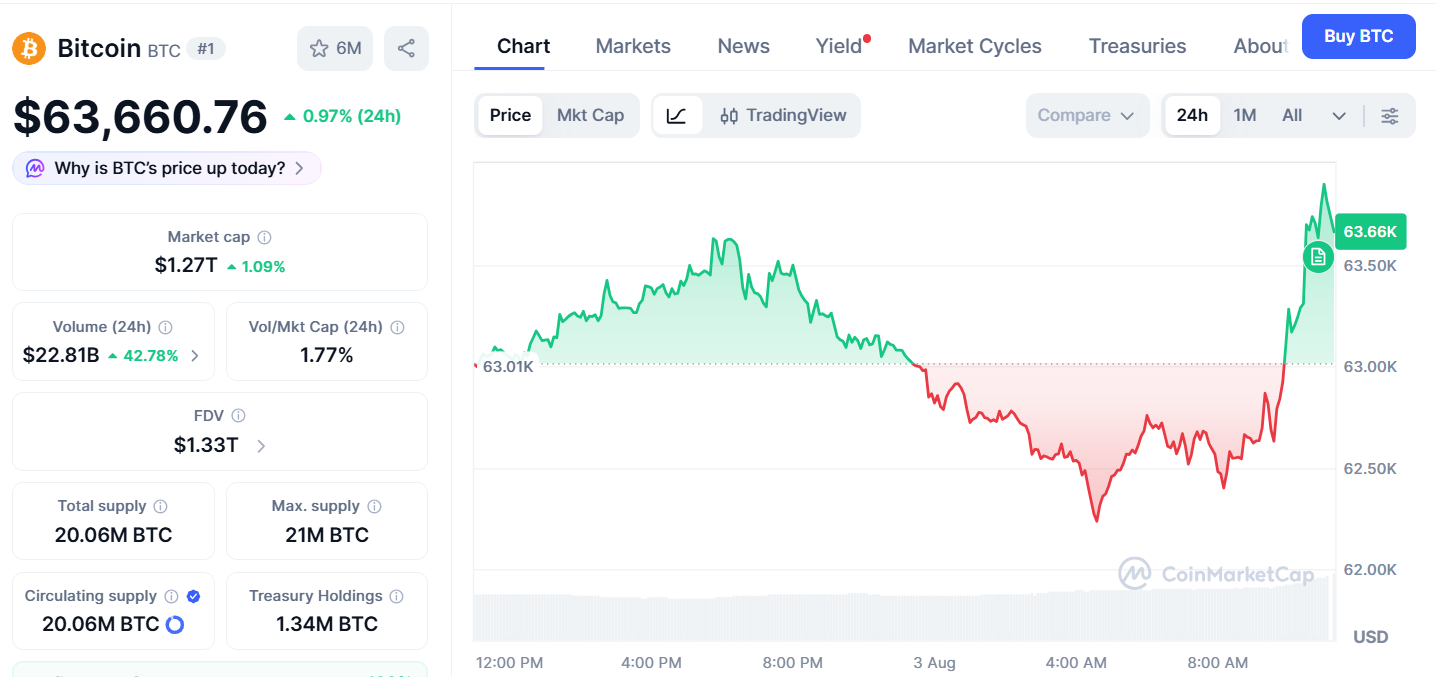
As the options expire worthless or are exercised, that particular web of hedging requirements dissolves. This clearing of the slate fundamentally alters short-term market positioning, freeing dealers from the obligation to mechanically buy or sell based on minor price fluctuations in the underlying asset.
Inter-Market Divergence: Altcoins Steal the Spotlight
One of the most fascinating data points to emerge from the post-expiry landscape is the behavior of major altcoins. While Bitcoin consolidated and cooled off near $83,600—comfortably above its pre-breakout range—capital did not flee the cryptocurrency asset class entirely.
Instead, a pronounced rotation occurred:
- XRP: Surged roughly 15% over a seven-day window.
- Solana (SOL): Posted solid gains of approximately 9% over the same period.
This divergence provides clear evidence that the September 25 expiry did not trigger a systemic "risk-off" event. Rather, liquidity remained deeply embedded within the ecosystem, flowing flexibly between Bitcoin and high-beta layer-1/layer-2 alternatives.
Official Responses and Industry Perspectives
Market commentators, derivatives analysts, and institutional risk managers have weighed in heavily on the smooth execution of the September options expiry, offering valuable context on what this means for the broader crypto economy.
Renowned derivatives analysts noted that the market has matured significantly compared to previous cycles in 2021 and 2022. In earlier eras, expiries of even a fraction of this size routinely caused violent market dislocations, cascade liquidations on leveraged exchanges, and widespread panic.
“The smooth digestion of a $15.6 billion options book demonstrates a structural evolution in how crypto derivatives are handled,” remarked one senior liquidity strategist. “We are seeing a more sophisticated participant base, deeper order books, and improved risk-management practices across both centralized and decentralized venues. The bogeyman of ‘max pain’ is often exaggerated by social media pundits who fail to account for how professional desks actively roll, hedge, and neutralize their delta exposure days before the actual settlement hour.”
Furthermore, exchange representatives highlighted that the decentralized and transparent nature of order books on platforms like Deribit allows systemic risks to be priced in well in advance. Because the multi-billion-dollar build-up was visible for weeks, market participants had ample time to adjust their risk parameters, preventing any single entity from being caught in an untenable position when the settlement bell rang.
Implications: What Lies Ahead for Bitcoin and the Wider Crypto Market?
With the massive September quarterly book safely in the rear-view mirror, market participants are shifting their focus from derivatives mechanics to the fundamental macro and micro drivers that will dictate Bitcoin’s trajectory for the remainder of the year.
1. Shift from Derivatives to Spot-Driven Price Action
For weeks, the gravitational pull of 182,000 BTC worth of open interest heavily influenced day-to-day price action. Now that this weight has been lifted, Bitcoin’s next major price move will depend far less on traders managing expiring option strikes and far more on organic spot demand. If buyers continue to step in at current price floors, the path of least resistance remains skewed to the upside.
2. The Continued Relevance of ETF Flows and Macro Conditions
While clearing a $15.6 billion derivatives hurdle is a major milestone, Bitcoin does not exist in a vacuum. Spot Exchange-Traded Fund (ETF) inflows, macroeconomic monetary policies (such as Federal Reserve rate decisions), and global liquidity trends will continue to serve as primary catalysts. The resilience shown during the expiry week suggests that institutional conduits remain healthy and capable of absorbing supply shocks.
3. Heightened Appetite for Altcoin Rotation
The outperformance of assets like XRP and Solana during Bitcoin’s consolidation phase highlights a healthy rotation of capital. When altcoins can rally independently while the flagship asset pauses, it typically indicates a broadening market confidence rather than a narrow, speculative mania driven solely by BTC maximalism. Investors are actively seeking yield and growth across multiple blockchain ecosystems, setting the stage for a dynamic Q4.
Conclusion
The passage of the $15.6 billion Bitcoin options expiry without a spot market blow-up is a testament to the growing maturity of the digital asset industry. By successfully absorbing a staggering volume of hedging exposure while allowing capital to flow organically into altcoins, the market has proven its resilience. As the derivatives slate is wiped clean, Bitcoin stands on solid ground in the mid-$83,000s, ready for its next chapter of price discovery dictated by genuine spot demand and macroeconomic tailwinds.